When central banks raise or cut their benchmark rates, the change reaches Main Street through one channel first: the price of borrowed money. A small business with a term loan, a credit line or a business credit card sees that price move within one or more billing cycles, because most short-term business credit carries a variable rate. Fixed-rate loans already signed do not change, but the next loan a owner shops for will price at the new level.
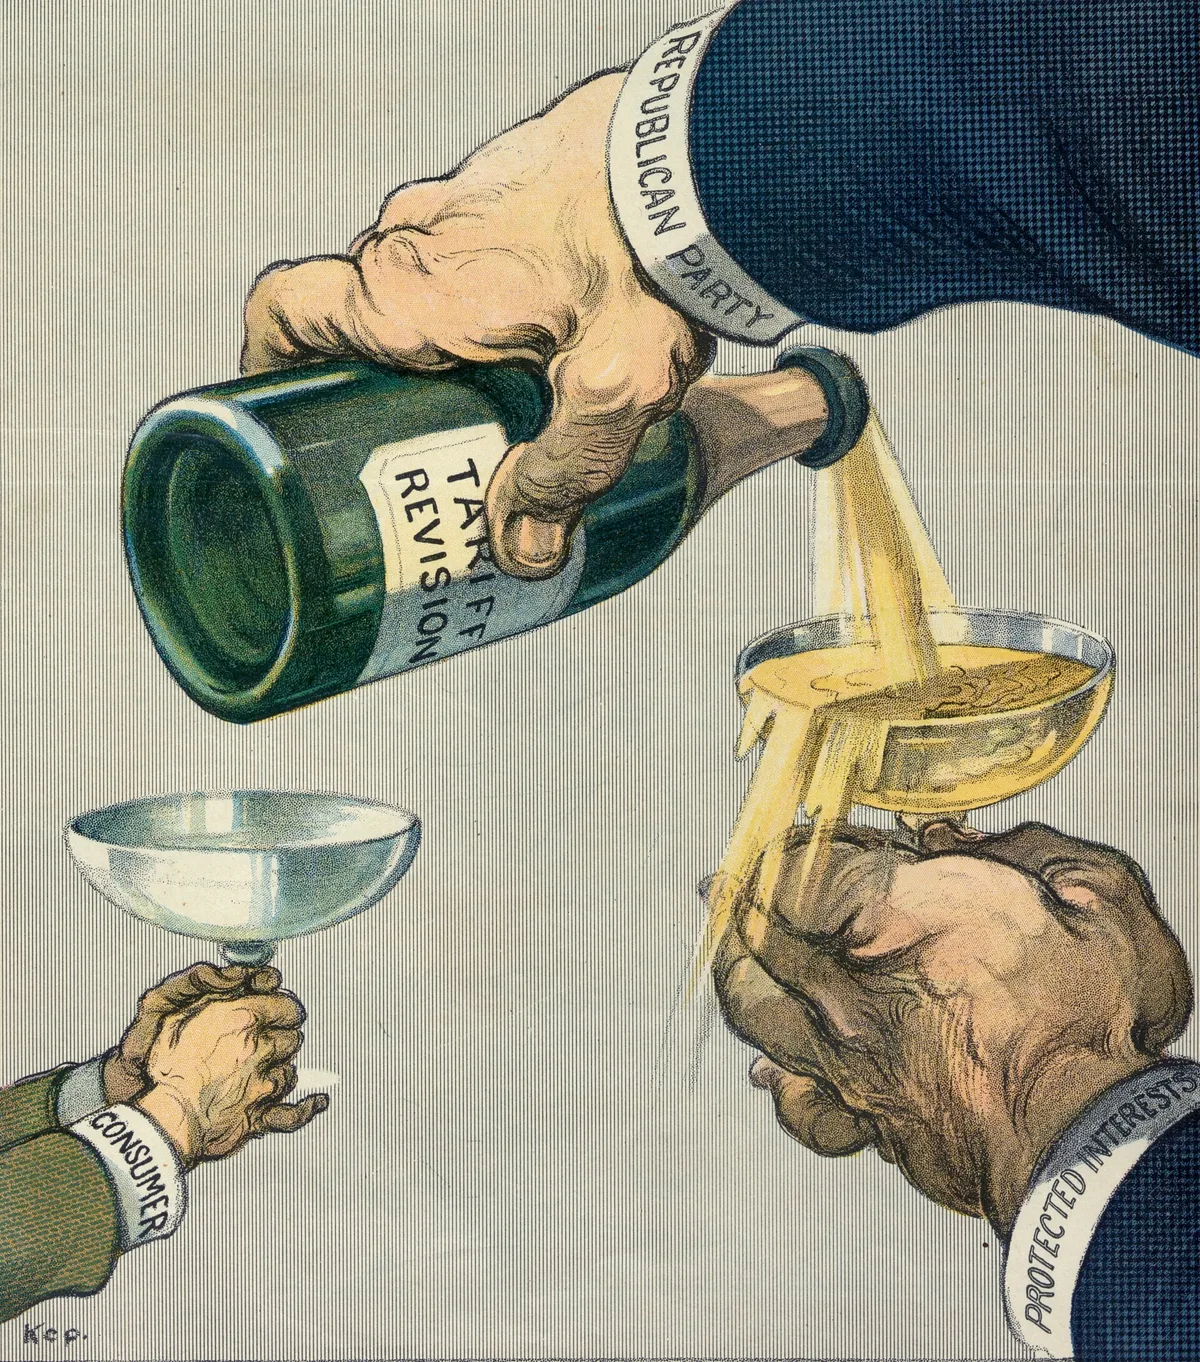
The effect is not abstract. Interest is, in plain terms, "a charge for borrowed money generally a percentage of the amount borrowed," as Merriam-Webster defines it. For a business, that charge sits alongside rent and payroll as a fixed claim on cash flow. When the rate rises, the claim grows; when it falls, cash is freed for other uses.
This explainer walks through how those decisions reach a small firm's loans, inventory and hiring, and what an owner can reasonably do about it. It is general information, not financial or legal advice.
What is interest, and why does the rate matter so much?
Interest is the payment a borrower makes to a lender above the amount borrowed, at an agreed rate. Wikipedia's economics entry describes it as a payment from borrower to lender of an amount above repayment of the sum borrowed, at a particular rate. The rate is usually quoted as an annual percentage of the principal, the original loan amount.
The size of that percentage matters because it compounds across the life of a loan. As a worked example, Bankrate calculates that a $10,000 loan at a 10% annual rate repaid over five years costs about $2,748.23 in interest over the life of the loan. The same loan at a lower rate would cost meaningfully less, and at a higher rate, more. That is the arithmetic every borrowing decision runs on.
Lenders also charge fees beyond the rate. Bankrate recommends comparing the annual percentage rate, or APR, which folds the interest rate and most fees into one figure, rather than the headline rate alone. For a small business comparing two loan offers, the APR is the closer approximation of the true cost.
How do central bank decisions reach a small business loan?
A central bank sets a short-term benchmark rate at which banks lend to one another. Commercial lenders then price their own products off that benchmark plus a margin for risk and overhead. When the benchmark moves, rates on variable-rate credit products tend to move with it.
Most business credit lines and business credit cards carry variable rates, so the pass-through is fairly direct. Fixed-rate term loans, equipment loans and mortgages do not reset, but new fixed-rate lending prices off the prevailing market level. A firm refinancing or expanding during a high-rate period pays the going rate; the same firm that locked a low fixed rate earlier keeps its old terms.
Two features of the loan determine how much of the move a borrower feels. One is fixed versus variable: a fixed rate does not change over the loan's life, while a variable rate may move up or down, as Bankrate explains. The other is simple versus compound interest, meaning whether interest is charged only on the principal or also on previously accrued interest. Business owners should know which structure their loan uses before rates move.
What does a higher rate do to inventory and working capital?
Inventory is where rate changes hit hardest for retailers, wholesalers and anyone holding stock. Goods bought on a credit line carry financing cost from the day they are purchased until they are sold and the invoice is collected. A higher rate raises the carrying cost of every unit on the shelf, which squeezes the margin between what the goods cost and what they sell for. This connects to our earlier piece, Chapter 11 Explained: Automatic Stay, DIP Financing and How Reorganization Actually Works.
Owners respond in predictable ways. They trim order sizes, negotiate longer payment terms with suppliers, or slow the rebuild of stock after a strong season. None of these is wrong, but each carries a trade-off: thinner inventory can mean missed sales if demand arrives before the next order lands.
There is also a lender-side effect worth understanding. Rates on credit products depend partly on the borrower's own financial health, since lenders charge more when they judge repayment risk higher, per Bankrate's explanation of how rates are set. So a rate environment that strains cash flow can also weaken the credit profile that determines the next loan's pricing. Weak quarters and expensive credit can reinforce each other.
How do rates shape hiring and expansion decisions?
A new hire is an investment paid back over months and years of productivity. When borrowing is cheap, financing that investment, or the equipment the hire needs, is easier to justify. When borrowing is expensive, the same hire must clear a higher bar, and marginal positions get delayed or left unfilled.
The same logic applies to expansion: a second location, new equipment, a larger lease. Higher rates raise the hurdle for projects financed with debt, so fewer projects clear it. Multiply that hesitation across thousands of firms and it becomes a broad slowdown in small-business investment, which is the mechanism policymakers are deliberately engaging when they move rates up to cool demand or down to support it.
What this means in practice: rate moves are not noise. They are a signal about how expensive growth will be for the next several quarters, and firms that plan around them, rather than react to them, tend to make steadier decisions.
Practical steps for owners in any rate environment
Our analysis of how these mechanics fit together points to a short checklist that applies whether rates are rising or falling.
- Know your rate structure. List every credit facility with its rate, whether it is fixed or variable, and its reset terms. Variable balances are the ones that move when the benchmark moves.
- Compare APRs, not headline rates. Because fees vary widely between lenders, the APR gives a truer comparison, as Bankrate's guidance notes.
- Model the cost of carrying inventory. Estimate what a month of stock on the shelf costs at the current line-of-credit rate, and let that number guide order sizes.
- Time fixed-rate decisions deliberately. If a major purchase is planned, the fixed-versus-variable choice determines whether today's rate follows you for years or resets with the market.
- Keep financial records current. Since lenders price off credit history and debt-to-income measures, clean books and timely payments are the part of the rate equation an owner actually controls.
Owners facing a specific financing decision should also read the underlying documents closely, because loan agreements are contracts with real consequences. Our guides to Seven Contract Provisions Every Small Business Owner Should Understand and to how Chapter 11 reorganization actually works cover the legal side of debt that rate discussions often skip. Readers following this should also see Seven Contract Provisions Every Small Business Owner Should Understand.
Where the evidence stops and judgment begins
The mechanics above are well established: interest is the cost of borrowed money, benchmark rates feed lender pricing, and variable-rate credit passes those moves through to borrowers, as the definitions and examples from Merriam-Webster, Wikipedia and Bankrate show. What no general explainer can supply is the current level of any benchmark rate or a forecast of where it goes next, and this article deliberately does not try.
What remains unknown for any individual business is the mix of its own debt, the terms of its credit agreements and the timing of its growth plans. Those specifics, not the central bank's decision alone, determine how much a rate move actually costs a given firm. The owner's job is to map the specifics, then decide which costs are worth carrying.