Currency exchange for business comes down to one question: when you pay a supplier in another currency, how much does that money actually cost you? The answer is rarely the rate on a converter screen. Between the mid-market rate and the money that lands in your supplier's account sit a bid-ask spread, a transfer fee, and the risk that the rate moves between the day you agree a price and the day you pay it.
For a first-time importer, those three layers quietly change margins. A product quoted at a fixed price in euros or yen is not a fixed cost in dollars until the payment is made. This piece explains what the quoted rate means, where the hidden costs sit, and what an importer can realistically do about each one.
What is the mid-market rate, and why won't you get it?
The mid-market rate is the midpoint between what buyers will pay and what sellers will accept for a currency. It is the rate you see on converter tools. According to Xe, its converter uses the mid-market rate for informational purposes only, and states plainly that you will not receive that rate when sending money. The same gap shows up everywhere: Exchange-Rates.org showed 1 US dollar equal to 0.8889 euros at one recent update, with a note that rates fluctuate every minute.
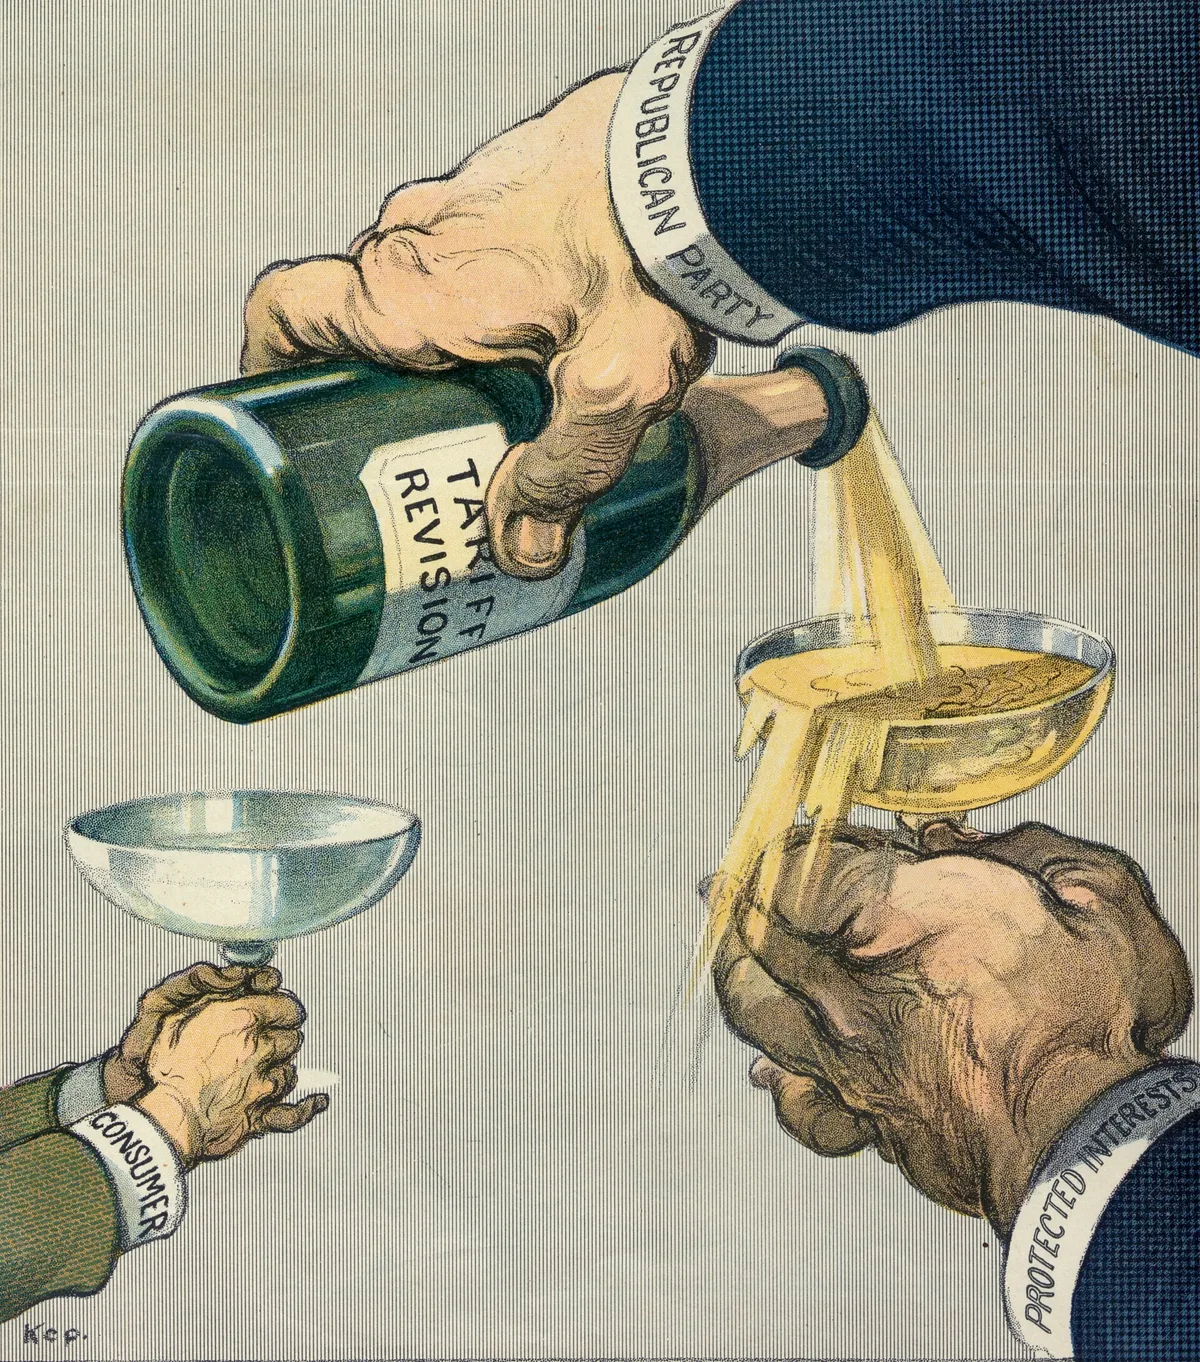
Why the gap? As Calculator.net explains in its glossary of currency terms, real-world exchanges with brokers, banks or payment businesses set their own rates at bid-ask spreads that return a percentage as profit. The bid price is what a buyer will pay; the ask price is what a seller accepts; the difference between them is the spread. Some providers call that profit a fee or commission. Either way, it comes out of your payment.
Where do the fees actually sit in an international payment?
Importer payments usually carry three separate charges, and they stack:
- The spread. The provider converts your dollars at a rate worse than mid-market. On a large supplier invoice, even a small percentage difference is real money.
- The transfer fee. A flat or tiered charge for moving the funds. Some services advertise low or zero transfer fees and recover the cost in the spread instead, which is why comparing only the headline fee misleads.
- Correspondent or receiving charges. Money crossing borders often passes through intermediary banks, and the supplier's bank may deduct a receiving fee. Ask the supplier what actually arrived on their last payment.
The practical check is simple: ask the provider for the total landed amount in the supplier's currency for a fixed dollar amount, including every fee. Compare that figure across providers rather than comparing quoted rates.
How does rate movement change a quoted product cost?
Exchange rates move continuously. Exchange-Rates.org notes that currencies trade around the clock, five days a week, and that its own converter updates every few minutes. A supplier price agreed in a foreign currency is therefore a moving target in dollar terms until you pay it. If the dollar weakens between order and payment, the same invoice costs you more dollars than you budgeted. If the dollar strengthens, it costs less. Importers on thin margins can lose the entire profit on an order to an unfavorable move.
Timing also has a smaller, operational dimension. Exchange-Rates.org points to the hours when the New York and London trading sessions overlap as a period of good liquidity, because peak activity in two of the largest currency markets coincides. Liquidity affects how tightly a provider can price a conversion. That is a scheduling detail, not a strategy, but first-time importers often overlook it.
What can an importer do about currency risk?
There are three broad responses, in rising order of commitment:
- Invoice in dollars. If the supplier agrees to price in USD, the currency risk moves to them, and they will usually price that into the quote. You trade a known markup for an unknown exposure.
- Convert promptly. Paying or converting soon after agreeing a price shrinks the window in which the rate can move. The trade-off is giving up any favorable movement.
- Hedge. Forward contracts let a business lock a rate now for a payment due later. Hedging is a discipline question as much as a pricing one: it removes the surprise in both directions, which is exactly the point for a business that budgets to a margin rather than speculates on currencies.
What this means for a first-time importer: decide deliberately which of these you are doing. The worst position is the accidental one, where the payment date, the currency and the provider are all chosen by default and the exposure is discovered after the invoice lands.
How should a new importer set up the payment side?
Treat the payment process like any other compliance step in importing, with the same care you would give entry paperwork. Our analysis of the sequence, drawn from how currency markets and payment providers actually operate: For related coverage, see Customs Bonds and the Import Entry Process: From Arrival to Liquidation.
- Find out the supplier's preferred currency and payment method before you negotiate, because the answer changes the quote you should be comparing.
- Get the mid-market rate at the moment you agree the price, and record it. Converter tools such as Xe and Exchange-Rates.org publish it, and Calculator.net notes the interbank rate is the wholesale rate banks use between themselves, the reference point beneath retail quotes.
- Ask two or three providers for the total supplier-received amount on a sample payment, not the rate.
- Decide your policy on hedging before your first large order, even if the policy is to accept the risk.
- Reconcile each payment against the supplier's confirmation of what arrived, so fees and shortfalls surface immediately.
Currency is one cost layer among several in an imported product's landed price. Duties, entry requirements and the transfer of risk between buyer and seller each have their own rules; our trade coverage follows them in detail. For the shipping side of the same bargain, see how Incoterms assign risk between importers and exporters, and for the duties side, how customs bonds and the entry process work from arrival to liquidation. This connects to our earlier piece, Incoterms Explained: What Importers and Exporters Get Wrong About Risk Transfer.
What should a first-time importer take away?
The evidence here supports three takeaways. First, the mid-market rate is a reference, not a price; Xe says so directly about its own converter, and Calculator.net explains the spread mechanism that stands between that reference and what you pay. Second, compare providers on total delivered cost, because fees hide in spreads, transfer charges and receiving-bank deductions. Third, a foreign-currency invoice is an open exposure until it is paid, and the importer who decides in advance how to handle that exposure, whether by pricing in dollars, converting promptly or hedging, budgets with better information than one who does not.
The trade-off worth naming: locking certainty costs something, whether it is a supplier's dollar-price markup or a hedging cost, and accepting rate risk costs nothing until the market moves. Which cost a business should carry depends on its margins and its cash position, and that judgment, unlike the mechanics above, has no default answer.